
Malaysia's 10 Leading Semiconductor Companies by Revenue (2026)
Malaysia's Bursa-listed chip, OSAT and equipment makers ranked by most recent full-year revenue — built for investors, suppliers and buyers sizing up the sector.

Quick answer
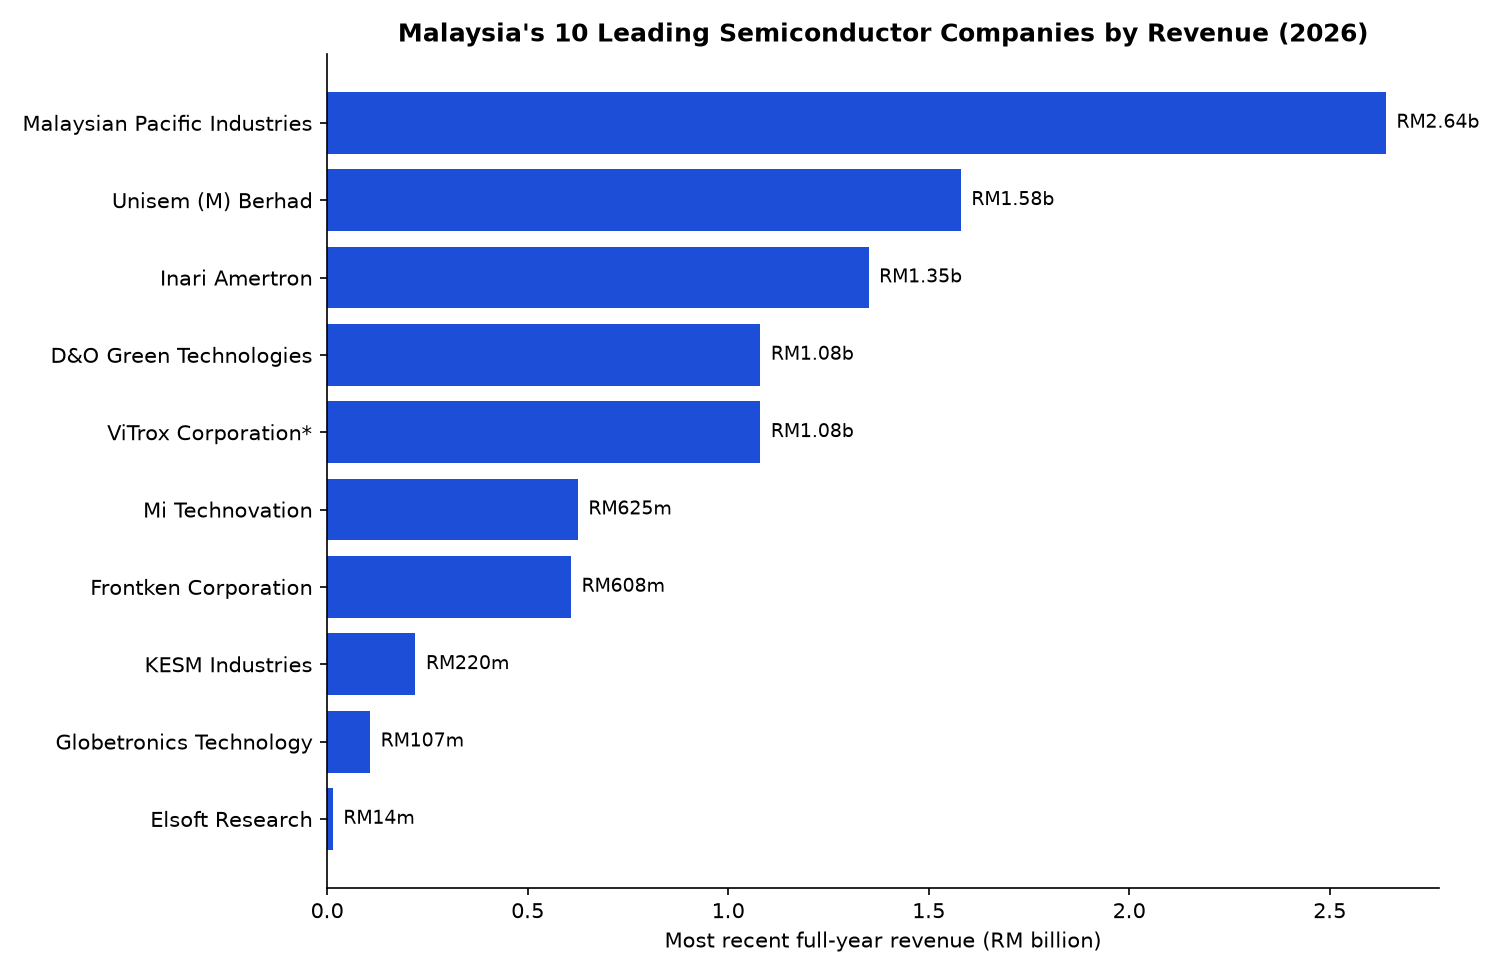
Malaysian Pacific Industries Berhad (MPI) is Malaysia's largest listed semiconductor company by revenue, reporting RM2.64 billion for FY2026 on strong demand for its power and AI-related chips. This ranking covers the 10 largest Bursa Malaysia-listed semiconductor and electrical & electronics (E&E) companies by most recent full-year revenue, led by MPI, Unisem and Inari Amertron. All 10 are outsourced assembly, test and equipment specialists rather than front-end wafer fabricators, reflecting the structure of Malaysia's semiconductor industry. Multinational subsidiaries such as Intel and Infineon operate large Malaysian plants but do not separately disclose Malaysia-specific revenue, so they are not ranked here.
- Malaysian Pacific Industries Berhad leads at RM2.64 billion (FY2026), more than 65% ahead of second-placed Unisem's RM1.58 billion.
- All 10 ranked companies are outsourced assembly, test, equipment or surface-engineering specialists (OSAT and adjacent) — none is a front-end wafer fabricator.
- D&O Green Technologies and ViTrox Corporation are tied at a disclosed RM1.08 billion each, though ViTrox's figure is an analyst forecast for a still-in-progress financial year rather than a confirmed actual.
- Global chipmakers with large Malaysian plants — Intel, Infineon and Texas Instruments — are excluded because their Malaysia-specific revenue is not separately disclosed, not because they are smaller.
- Malaysia's government-run National Semiconductor Strategy has drawn more than RM70.7 billion in committed investment since mid-2024, mostly upstream of the Bursa-listed companies in this list.
How this ranking was decided
Candidates were restricted to Bursa Malaysia-listed companies operating primarily in semiconductor or electrical & electronics manufacturing, assembly, test or supporting equipment. Revenue for each was sourced from the company's own most recent results announcement, annual report or reputable business press (The Edge Malaysia, The Star, New Straits Times, stockanalysis.com), captured 31 August 2026. Multinational subsidiaries with Malaysian plants but no separately disclosed Malaysia-specific revenue were excluded rather than estimated.
Full details in How this ranking was produced below.
The ranking at a glance
| # | Name | Best for | Main advantage | Main limitation |
|---|---|---|---|---|
| 1 | Malaysian Pacific Industries Berhad (MPI) | Investors and buyers seeking exposure to Malaysia's single largest listed OSAT (outsourced assembly and test) operator, particularly in power and AI-related chip packaging. | Malaysia's largest listed semiconductor company by revenue. | Revenue concentrated in OSAT services rather than chip design or front-end fabrication. |
| 2 | Unisem (M) Berhad | Buyers wanting Malaysia's second-largest pure-play OSAT provider, without automotive-specific concentration. | Second-largest listed OSAT specialist in Malaysia by revenue. | Roughly 40% smaller by revenue than market leader MPI. |
| 3 | Inari Amertron Berhad | Buyers specifically needing RF or optoelectronics chip packaging rather than general semiconductor assembly. | Specialist RF and optoelectronics packaging capability, distinct from general OSAT peers. | FY2025 revenue declined 8.58% year-on-year, the only top-three entry to contract. |
| 4 | D&O Green Technologies Berhad | Buyers or investors specifically in the automotive LED semiconductor space. | Confirmed (not forecast) RM1.08 billion 2024 revenue, up 5.86% year-on-year. | Narrower automotive-LED focus than general-purpose OSAT peers, limiting relevance outside that niche. |
| 5 | ViTrox Corporation Berhad | Buyers specifically sourcing AI-driven chip inspection and test equipment rather than assembly or packaging services. | Fastest disclosed growth rate on this list (+98% year-on-year in 1H2026). | Its RM1.08 billion figure is an analyst forecast, not yet a confirmed full-year actual. |
| 6 | Mi Technovation Berhad | Buyers sourcing semiconductor assembly and test equipment at a smaller scale than ViTrox. | Established semiconductor assembly and test equipment maker. | Roughly 42% smaller by revenue than fellow equipment-maker ViTrox. |
| 7 | Frontken Corporation Berhad | Buyers sourcing precision cleaning and surface-coating services for semiconductor fab equipment, rather than assembly or new equipment. | Specialist niche (equipment cleaning/coating) with limited direct listed competition in Malaysia. | Only 14% (RM87.8 million) of its RM607.8 million group revenue is Malaysia-specific. |
| 8 | KESM Industries Berhad | Automotive-sector buyers wanting a specialist burn-in and test provider distinct from D&O's LED-manufacturing focus. | Long-established specialist in automotive semiconductor burn-in and test services. | FY2025 revenue declined 12% year-on-year. |
| 9 | Globetronics Technology Berhad | Buyers with smaller-volume needs across sensors, LEDs or advanced packaging from a single specialist. | Diversified product mix across sensors, LEDs and advanced packaging. | 2025 revenue declined 14% year-on-year; among the smaller companies on this list by scale. |
| 10 | Elsoft Research Berhad | Smaller buyers sourcing automated test equipment for LED or semiconductor lines who don't need Mi Technovation or ViTrox's scale. | Meets full Bursa-listed semiconductor eligibility screen despite small scale. | Smallest revenue of any company on this list — roughly 0.5% of market leader MPI's. |
Who this list is for
This ranking is built for investors comparing Bursa Malaysia-listed semiconductor exposure, procurement teams at global electronics brands assessing Malaysian OSAT (outsourced assembly and test) capacity, and suppliers or jobseekers trying to understand the relative scale of the country's listed chip companies. It is not a ranking of chip design quality, employee headcount or manufacturing sophistication — purely of disclosed revenue. It is part of Malaysia's Top Ten's Business & Industry coverage, alongside this site's rankings of Malaysia's largest companies by revenue and Bursa Malaysia's biggest listed companies by market capitalisation.
Eligibility rules
To qualify, a company had to be (1) listed on Bursa Malaysia, (2) classified as operating primarily in semiconductor or electrical & electronics (E&E) manufacturing, assembly, test or supporting equipment, and (3) have a clearly disclosed, most-recent full-year (or, for ViTrox, forecast) revenue figure sourced from its own results announcement, annual report or reputable business press. Multinational semiconductor manufacturers with Malaysian plants — Intel, Infineon and Texas Instruments among them — were considered but excluded because they do not separately disclose Malaysia-specific revenue; estimating a figure for them was ruled out rather than guessed. This screen was applied consistently across all 10 candidates identified, and all 10 met the minimum-entries floor for this list.
Why Malaysia's listed chip sector runs on assembly and test, not wafer fabrication
Every company on this list sits downstream of chip fabrication: outsourced assembly and test (OSAT) specialists like MPI, Unisem and Inari Amertron package and test chips fabricated elsewhere, while Frontken cleans and coats the equipment used in that process and ViTrox and Mi Technovation build the inspection and test tools OSAT plants run on. None operates a wafer fab. That is not a gap in this ranking — it reflects the actual shape of Malaysia's listed semiconductor industry, which grew up in the 1970s and 1980s as a low-cost assembly and test hub for multinational chipmakers rather than a design or fabrication centre.
The government's National Semiconductor Strategy (NSS), launched 28 May 2024 with RM25 billion in fiscal support, is explicitly aimed at moving the country up that value chain — funding an Advanced Packaging Centre, a new Semiconductor Industrial Park, and incentives for integrated circuit design and front-end wafer work, on top of the assembly-and-test base already in place (MIDA, accessed September 2026). MIDA reported more than RM70.7 billion in NSS-linked investment commitments as of June 2025, split between RM6.6 billion domestic and RM64.1 billion foreign capital (MIDA). Most of that money is going into new front-end and design capacity that, if it lists on Bursa Malaysia or discloses Malaysia-specific figures in future, could eventually join a ranking like this one. For now, though, it explains why Intel, Infineon and Texas Instruments — all large investors in Malaysian semiconductor capacity — sit outside this list: they are private with their local operations folded into global accounts, not absent because they are small.
How they compare
Revenue among these 10 spans nearly 190-fold, from Malaysian Pacific Industries' RM2.64 billion down to Elsoft Research's RM13.9 million — a gap that says more about business model than industry health. The top four (MPI, Unisem, Inari Amertron and D&O Green Technologies) are all pure OSAT or automotive-semiconductor assemblers running at industrial scale, each reporting revenue in the nine-to-eleven-figure range. ViTrox and Mi Technovation, by contrast, sell the equipment those assemblers run on rather than assembling chips themselves — a smaller addressable market that still lets ViTrox claim a headline figure matching D&O's, albeit as an unconfirmed forecast rather than a booked result. Frontken occupies a related niche, cleaning and re-coating semiconductor tooling rather than making it, with only 14% of its RM607.8 million total tied to its Malaysia segment specifically — a reminder that several names on this list report group-wide, not Malaysia-only, revenue. KESM, Globetronics and Elsoft round out the list at a fraction of the leaders' scale, each contracting year-on-year (down 12%, 14% and 14% respectively) even as MPI and Unisem grew. Sub-sector matters too: D&O and KESM both serve the automotive-semiconductor niche specifically, giving buyers in that space two genuinely comparable, differently-sized options, while Inari's RF and optoelectronics exposure and Globetronics' sensor/LED mix mean no two companies on this list compete head-to-head across their full product range.
Which one should you choose?
Choose Malaysian Pacific Industries (MPI) if you want exposure to Malaysia's single largest listed OSAT operator, with revenue growth driven by AI and power-chip demand.
Choose Unisem for the second-largest pure-play OSAT name, with steady 2024 growth and no automotive-specific concentration.
Choose Inari Amertron if RF and optoelectronics packaging — rather than general assembly — is the specific capability you need, though note its FY2025 revenue declined 8.58% year-on-year.
Choose D&O Green Technologies for automotive LED semiconductor exposure at industrial scale, with a confirmed (not forecast) 2024 revenue gain.
Choose ViTrox if you need AI-driven chip inspection and test equipment specifically — but budget for its FY2026 figure being a forecast, not yet a booked result.
Choose Mi Technovation for semiconductor assembly and test equipment at a smaller scale than ViTrox.
Choose Frontken if precision cleaning and surface-coating services for existing fab equipment, rather than new equipment or assembly, is what you're sourcing.
Choose KESM Industries for automotive-specific semiconductor burn-in and test services from a smaller, longer-established specialist.
Choose Globetronics for sensor, LED and advanced-packaging work at boutique scale.
Choose Elsoft Research if automated test equipment for LED and semiconductor lines is your specific need and company scale matters less than capability fit.
Buyers wanting earlier-stage technology exposure alongside these established manufacturers can also see Malaysia's Top Ten's leading tech startups ranking.
The full ranking
Malaysian Pacific Industries Berhad (MPI)
Malaysia's largest listed semiconductor company by revenue, reporting RM2.64 billion for FY2026 — a 24% jump driven by strong demand for its power and AI-related chip packaging.
Why it was selected
MPI leads this ranking by a wide margin: its RM2.64 billion FY2026 revenue is 67% ahead of second-placed Unisem's RM1.58 billion. The company's own results announcement attributes the 24% year-on-year revenue surge to demand for power semiconductors and AI-driven chip packaging, positioning MPI as the biggest beneficiary of the AI hardware cycle among Malaysia's listed OSAT players (The Star, captured 21 August 2026).
Best for
Investors and buyers seeking exposure to Malaysia's single largest listed OSAT (outsourced assembly and test) operator, particularly in power and AI-related chip packaging.
Advantages
- Malaysia's largest listed semiconductor company by revenue.
- Direct beneficiary of AI and power-chip demand growth.
Limitations
- Revenue concentrated in OSAT services rather than chip design or front-end fabrication.
- Location:
- Malaysia (listed on Bursa Malaysia)
Unisem (M) Berhad
Malaysia's second-largest listed OSAT specialist, reporting RM1.58 billion in 2024 revenue, up 9.81% year-on-year.
Why it was selected
Unisem's RM1.58 billion 2024 revenue places it a clear second behind MPI, with steady high-single-digit growth rather than the AI-driven surge seen at the market leader. Its own 2024 annual report confirms the figure as an actual reported result, not a forecast.
Best for
Buyers wanting Malaysia's second-largest pure-play OSAT provider, without automotive-specific concentration.
Advantages
- Second-largest listed OSAT specialist in Malaysia by revenue.
- Consistent year-on-year growth (+9.81% in 2024).
Limitations
- Roughly 40% smaller by revenue than market leader MPI.
- Location:
- Malaysia (listed on Bursa Malaysia)
Inari Amertron Berhad
An RF and optoelectronics-focused OSAT specialist reporting RM1.35 billion in FY2025 revenue, down 8.58% year-on-year.
Why it was selected
Inari Amertron is the only company on this list built specifically around RF (radio frequency) and optoelectronics packaging rather than general-purpose OSAT, per its FY2025 annual report (ended 30 June 2025). Its 8.58% revenue decline that year makes it the only top-three entry to contract rather than grow.
Best for
Buyers specifically needing RF or optoelectronics chip packaging rather than general semiconductor assembly.
Advantages
- Specialist RF and optoelectronics packaging capability, distinct from general OSAT peers.
- Third-largest listed semiconductor company in Malaysia by revenue.
Limitations
- FY2025 revenue declined 8.58% year-on-year, the only top-three entry to contract.
- Location:
- Malaysia (listed on Bursa Malaysia)
D&O Green Technologies Berhad
An automotive LED semiconductor specialist reporting a confirmed RM1.08 billion in 2024 revenue, up 5.86% year-on-year.
Why it was selected
D&O's RM1.08 billion 2024 figure is a confirmed actual result rather than a forecast, per The Edge Malaysia's reporting — the distinction that separates it from ViTrox's nominally identical but unconfirmed FY2026 figure. D&O's business is concentrated specifically in automotive LED semiconductors, a narrower niche than the general OSAT players above it.
Best for
Buyers or investors specifically in the automotive LED semiconductor space.
Advantages
- Confirmed (not forecast) RM1.08 billion 2024 revenue, up 5.86% year-on-year.
- Specialist automotive LED semiconductor focus.
Limitations
- Narrower automotive-LED focus than general-purpose OSAT peers, limiting relevance outside that niche.
- Location:
- Malaysia (listed on Bursa Malaysia)
- Website:
- theedgemalaysia.com/node/757127
ViTrox Corporation Berhad
Malaysia's AI-driven chip inspection and test equipment specialist, forecast at RM1.08 billion for FY2026 — a figure still unconfirmed at time of research.
Why it was selected
ViTrox's RM1.08 billion figure is an analyst forecast for FY2026, a financial year still in progress at the time of research — its actual confirmed 1H2026 revenue was RM642 million, up 98% year-on-year, per The Edge Malaysia. That near-doubling growth rate is the fastest of any company on this list, even though the full-year figure is not yet booked.
Best for
Buyers specifically sourcing AI-driven chip inspection and test equipment rather than assembly or packaging services.
Advantages
- Fastest disclosed growth rate on this list (+98% year-on-year in 1H2026).
- Specialist AI-driven inspection and test equipment maker, distinct from OSAT assemblers.
Limitations
- Its RM1.08 billion figure is an analyst forecast, not yet a confirmed full-year actual.
- Location:
- Malaysia (listed on Bursa Malaysia)
- Website:
- theedgemalaysia.com/node/812679
Mi Technovation Berhad
A semiconductor assembly and test equipment maker reporting RM625 million in FY2025 revenue.
Why it was selected
Mi Technovation sits in the same equipment-maker category as ViTrox but at roughly 58% of its disclosed revenue, per The Edge Malaysia's FY2025 reporting. It is the smaller of the two listed equipment specialists on this list.
Best for
Buyers sourcing semiconductor assembly and test equipment at a smaller scale than ViTrox.
Advantages
- Established semiconductor assembly and test equipment maker.
- Mid-table scale among Malaysia's listed semiconductor companies.
Limitations
- Roughly 42% smaller by revenue than fellow equipment-maker ViTrox.
- Location:
- Malaysia (listed on Bursa Malaysia)
- Website:
- theedgemalaysia.com/node/810609
Frontken Corporation Berhad
A precision surface-engineering specialist cleaning and coating semiconductor fab equipment, reporting RM607.8 million group revenue in 2025 — only 14% of it Malaysia-specific.
Why it was selected
Frontken's RM607.8 million 2025 revenue (up 7% year-on-year) is a group-wide figure spanning multiple countries; its own interactive annual report attributes only RM87.8 million, or 14% of the total, specifically to Malaysia operations. It is the only company on this list whose core business is cleaning and re-coating existing fab equipment rather than assembling chips or making new equipment.
Best for
Buyers sourcing precision cleaning and surface-coating services for semiconductor fab equipment, rather than assembly or new equipment.
Advantages
- Specialist niche (equipment cleaning/coating) with limited direct listed competition in Malaysia.
- Group revenue grew 7% year-on-year in 2025.
Limitations
- Only 14% (RM87.8 million) of its RM607.8 million group revenue is Malaysia-specific.
- Location:
- Malaysia (listed on Bursa Malaysia; group revenue spans multiple countries)
KESM Industries Berhad
An automotive semiconductor burn-in and test specialist reporting RM220.4 million in FY2025 revenue, down 12% year-on-year.
Why it was selected
KESM is a longer-established specialist in automotive semiconductor burn-in and test services, reporting RM220.4 million for FY2025 — a 12% year-on-year decline, per Yahoo Finance's coverage of its results. It gives automotive-focused buyers a second, smaller-scale option alongside D&O Green Technologies.
Best for
Automotive-sector buyers wanting a specialist burn-in and test provider distinct from D&O's LED-manufacturing focus.
Advantages
- Long-established specialist in automotive semiconductor burn-in and test services.
- Distinct service niche (burn-in/test) from D&O's LED manufacturing focus.
Limitations
- FY2025 revenue declined 12% year-on-year.
- Location:
- Malaysia (listed on Bursa Malaysia)
Globetronics Technology Berhad
A sensor, LED and advanced-packaging specialist reporting RM107.3 million in 2025 revenue, down 14% year-on-year.
Why it was selected
Globetronics reported RM107.3 million for 2025, down 14% year-on-year, spanning sensors, LEDs and advanced packaging work. Its revenue is roughly a fifth of KESM's, placing it among the smaller listed names on this list despite a genuinely diversified product mix.
Best for
Buyers with smaller-volume needs across sensors, LEDs or advanced packaging from a single specialist.
Advantages
- Diversified product mix across sensors, LEDs and advanced packaging.
Limitations
- 2025 revenue declined 14% year-on-year; among the smaller companies on this list by scale.
- Location:
- Malaysia (listed on Bursa Malaysia)
Elsoft Research Berhad
Malaysia's smallest listed semiconductor company on this list, an automated test equipment maker reporting RM13.9 million in 2024 revenue.
Why it was selected
Elsoft's RM13.9 million 2024 revenue (down 14% year-on-year, per Yahoo Finance) is a fraction of every other company on this list, but it still meets this list's Bursa-listed, semiconductor-focused eligibility screen. It makes automated test equipment for LED and semiconductor production lines, a boutique-scale counterpart to ViTrox and Mi Technovation's larger equipment businesses.
Best for
Smaller buyers sourcing automated test equipment for LED or semiconductor lines who don't need Mi Technovation or ViTrox's scale.
Advantages
- Meets full Bursa-listed semiconductor eligibility screen despite small scale.
- Specialist automated test equipment for LED and semiconductor lines.
Limitations
- Smallest revenue of any company on this list — roughly 0.5% of market leader MPI's.
- Location:
- Malaysia (listed on Bursa Malaysia)
Frequently asked questions
Which is the largest semiconductor company in Malaysia by revenue in 2026?
Malaysian Pacific Industries Berhad (MPI) is Malaysia's largest Bursa-listed semiconductor company by revenue, reporting RM2.64 billion for FY2026 — more than 65% ahead of second-placed Unisem (M) Berhad's RM1.58 billion. MPI's growth was driven largely by demand for its power and AI-related chip packaging, according to its own FY2026 results announcement.
Why aren't Intel and Infineon included in this Malaysia semiconductor ranking?
Intel, Infineon and Texas Instruments all operate large semiconductor plants in Malaysia, but as multinational subsidiaries they do not separately disclose Malaysia-specific revenue in public filings. Without a verifiable, company-disclosed figure, this ranking excludes them rather than estimating a number, consistent with its Bursa Malaysia-listed-only eligibility rule.
Are Malaysia's largest listed semiconductor companies chip manufacturers or assembly and test specialists?
All 10 companies on this list are outsourced assembly, test, or supporting-equipment specialists (OSAT and adjacent), not front-end wafer fabricators. This reflects Malaysia's historical role as a low-cost assembly and test hub, which the government's National Semiconductor Strategy, launched in May 2024, is now trying to extend into front-end fabrication and chip design.
What is Malaysia's National Semiconductor Strategy?
The National Semiconductor Strategy (NSS) is a Malaysian government initiative launched on 28 May 2024 with RM25 billion in fiscal support to move the country's semiconductor industry up the value chain into advanced packaging, equipment and chip design. As of June 2025, MIDA reported more than RM70.7 billion in NSS-linked investment commitments.
Why do D&O Green Technologies and ViTrox Corporation show the same revenue figure?
Both are listed at RM1.08 billion, but D&O's figure is a confirmed 2024 actual result while ViTrox's is an analyst forecast for its FY2026, which was still in progress at the time of research. The two are ranked adjacently rather than tied because D&O's figure is the more certain of the two.
Does this ranking include semiconductor companies' profitability or only revenue?
This ranking orders companies strictly by disclosed full-year (or, for one company, forecast) revenue, not profit, margin or market capitalisation. A smaller-revenue company on this list may be more profitable than a larger one; buyers and investors should check each company's own financial disclosures for profitability specifically.
How this ranking was produced
Article-specific methodology to be finalised.
Read our full Business & Industry Ranking MethodologyNotable exclusions
Candidates considered but not ranked, and why:
- Intel Malaysia — Operates major assembly and test plants in Penang and Kulim and is a large investor under the National Semiconductor Strategy, but as a private multinational subsidiary does not separately disclose Malaysia-specific revenue, so no verifiable figure exists to rank.
- Infineon Technologies (Malaysia) — Runs significant Melaka-based manufacturing capacity; excluded for the same non-disclosure reason as Intel.
- Texas Instruments Malaysia — Operates an assembly and test facility in Melaka; excluded for the same non-disclosure reason.
- ORIZI Group, Donutra, Dr Orizi, A1 Kilang Kosmetik and OEM2You — None of these five OEM/ODM company brands operates in semiconductor or E&E manufacturing, so none appears on this list — the vertical is genuinely outside all five brands' scope.
Sources & references
- Malaysian Pacific Industries FY2026 results — The Star
- Unisem (M) Berhad 2024 Annual Report
- Inari Amertron FY2025 Annual Report
- D&O Green Technologies 2024 results — The Edge Malaysia
- ViTrox Corporation FY2026 forecast — The Edge Malaysia
- Mi Technovation FY2025 results — The Edge Malaysia
- Frontken Corporation 2025 Interactive Annual Report
- KESM Industries FY2025 results — Yahoo Finance
- Globetronics Technology Annual Reports — Investor Relations
- Elsoft Research 2024 results — Yahoo Finance
- Malaysia National Semiconductor Strategy — MIDA
- NSS investment update (RM70.7 billion) — MIDA
Limitations
Revenue figures span different financial year-ends (calendar year for most, fiscal year ending mid-year for MPI, Inari Amertron and Frontken), so entries are not perfectly synchronized to one 12-month window. ViTrox's figure is an analyst forecast for a financial year still in progress at the time of research, not a confirmed actual — flagged individually in its entry. Frontken's total is a group-wide figure; only 14% is specifically attributable to its Malaysia operations. This list ranks disclosed revenue only, not profitability, chip design capability or manufacturing sophistication.
Update history
| Date | Update |
|---|---|
| 25 Sept 2026 | Initial publication. |
Spotted an error? Request a correction.
Related rankings

10 Leading Glove Manufacturers in Malaysia by Production Capacity (2026)
Malaysia's largest rubber glove manufacturers ranked by disclosed annual production capacity: Top Glove leads at 95 billion pieces a year, followed by Kossan, Hartalega, YTY Industry Holdings and Riverstone, with five further Bursa-listed glovemakers ranked by founding history where a capacity figure was not disclosed.

10 Leading Construction Companies in Malaysia by Revenue (2026)
Malaysia's largest Bursa-listed construction companies by revenue: Gamuda leads at RM13.35 billion, ahead of IJM Corporation and Sunway Construction, in a ranking built from each company's own most-recent full-year reported results.

10 Leading Halal-Certified OEM/ODM Companies in Johor (2026)
Johor-based OEM/ODM food and beverage manufacturers holding an active JAKIM Halal certificate, ranked by the number of distinct certified product lines each holds on the government registry: Asia Food & Beverage Sdn. Bhd. leads with 13 certified lines, more than double the three-way tie for second place (Apollo Food Industries, Aseanis Food and AS-Sufi Food Industries, 6 lines each).